Work out your Capital Gains Tax, and report it with confidence.
A free calculator for property, shares and crypto at the 18% and 24% rates, plain-English guides, and step-by-step help when you want it for reporting to HMRC.
Free, no account or email needed. Independent, not HMRC.
Capital Gains Tax Calculator UK 2026/27
Estimate how much Capital Gains Tax you may owe on property, shares or other taxable gains using sale proceeds, purchase cost, allowable expenses, losses and your income.
Reviewed by the UKCapitalGainsTaxCalculator team · Methodology and assumptions
Calculator checked against GOV.UK and HMRC rules on (how we check).
Capital Gains Tax Calculator
Adjust figures - results update instantly.
Want your own figures checked line by line? Preview Your Full CGT Report (£4.99)
No CGT to pay on these figures. Free next step: check whether you still need to report the sale
Help with reporting it
The calculator and guides are free, and so is reporting on GOV.UK. If you want the rules in one place, your own figures checked, or every tax pack we publish, there are three optional downloads.
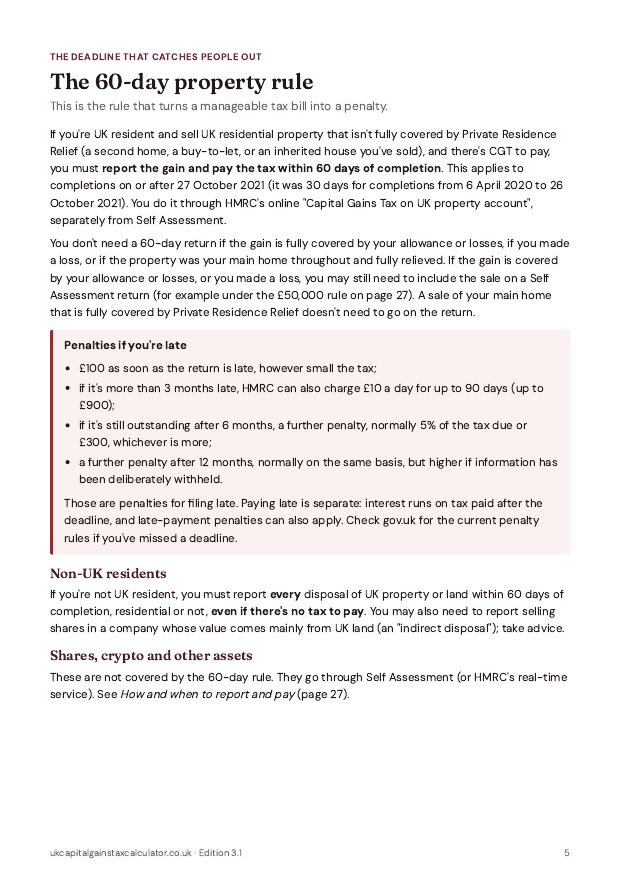
Capital Gains Tax Survival Pack
The rules, deadlines and reliefs for 2026/27 in plain English, with six worked examples and fill-in worksheets.
- The 60-day property deadline, step by step
- Share and crypto matching rules, with worksheets
- 2026/27 rates and the £3,000 allowance
£4.99 one-off · instant download · full refund on request
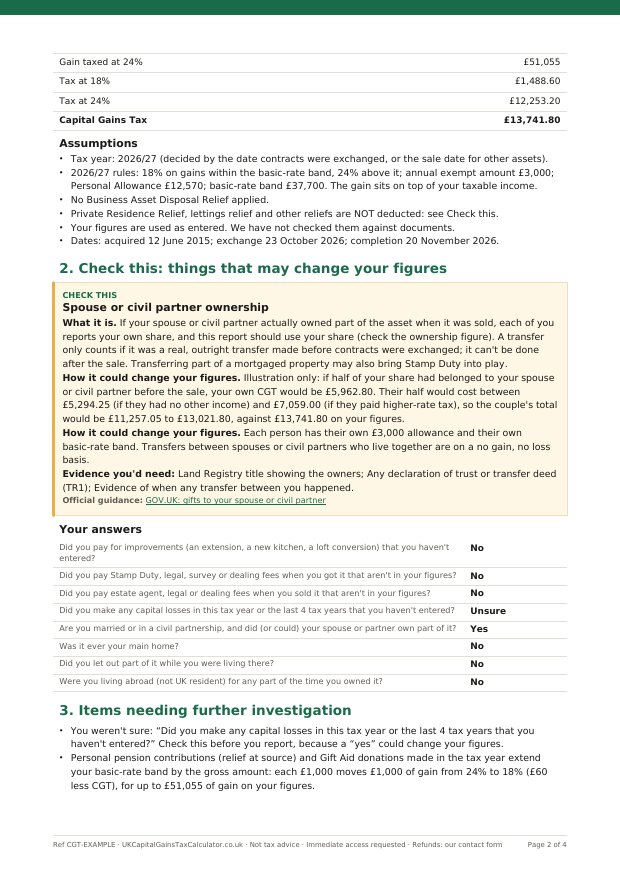
Your Full CGT Report
Every figure worked out from your own numbers, with a review of the costs, losses and reliefs that may be missing.
- Every 2026/27 figure worked out from your own numbers
- Your deadline, and what to report and when
- A 5 to 7-page report plus a costs tracker spreadsheet
£4.99 one-off · instant download · full refund on request
The 2026/27 Tax Pack Library
All seven of our 2026/27 tax packs: Capital Gains Tax, director's pay, pensions, home buying, sole trader, PAYE tax codes and new starters.
- Seven plain-English packs for 2026/27
- Download one at a time or all in one ZIP
- One payment, no subscription
£9.99 one-off · instant download · full refund on request
Reporting and paying Capital Gains Tax on GOV.UK is free, and HMRC’s guidance is free too. These downloads are optional. Not sure which fits? Compare them.
For 2026/27 Capital Gains Tax is 18% within your basic-rate band and 24% above it, after a £3,000 tax-free allowance - the same rates apply to shares, crypto and property.
Key figures
- Capital Gains Tax is 18% on gains within your basic-rate band and 24% above it, on gains made from 6 April 2026. GOV.UK CGT rates
- The tax-free allowance is £3,000 for each individual in 2026/27. GOV.UK CGT allowances
- If you sell UK residential property and CGT is due, you must report and pay it within 60 days of completion. GOV.UK report and pay CGT
- Other gains made in 2026/27 go on your Self Assessment return, due online and paid by 31 January 2028. GOV.UK Self Assessment deadlines
Checked 1 November 2026.
When to report and pay
- 60 daysUK residential property. Report and pay within 60 days of completion, through HMRC’s Capital Gains Tax on UK property account, if there is tax to pay.The 60-day rule →
- 31 January 2027Gains in 2025/26 (6 April 2025 to 5 April 2026). Report on your Self Assessment return and pay by 31 January 2027.CGT on your 2025/26 return →
- 31 January 2028Gains in 2026/27 on shares, funds, crypto and other assets. Report and pay through Self Assessment by 31 January 2028.How to report a gain →
- 4 yearsClaiming a loss. You have 4 years from the end of the tax year you made a loss to claim it, so it can reduce future gains.Claiming a loss →
Sources: GOV.UK, report and pay your Capital Gains Tax; GOV.UK, claiming losses.
Sold more than one thing this year? Pool them under one allowance
You get just one £3,000 annual exempt amount across all your disposals in a tax year - not £3,000 for each. Enter the gain on each disposal to see the correct combined Capital Gains Tax. Estimate only - not advice.
Three steps to estimate your CGT
Enter the disposal details
Add sale proceeds, purchase cost and allowable expenses such as legal fees, agent fees and improvement costs.
Add losses and income
Enter any capital losses to offset the gain. Add taxable income so the calculator can work out whether the gain falls at 18% or 24%.
Review the CGT estimate
See CGT at each rate, the exempt amount used, net proceeds after tax, and effective CGT rate on the gross gain.
Buy-to-let sold after 15 years
Bought in 2010 for £185,000. Sold in 2026/27 for £280,000. Higher-rate taxpayer.
| Gross gain | £95,000 |
| Less allowable costs (agent, legal, improvements) | −£12,000 |
| Less annual exempt amount | −£3,000 |
| Taxable gain | £80,000 |
| CGT at 24% | £19,200 |
Due within 60 days of completion. Try adjusting the figures in the calculator above.
Capital gains tax guides
In-depth guides to CGT rules, rates and allowances for 2026/27. Written for UK taxpayers, not accountants.
CGT on a Second Home
No Private Residence Relief, 60-day reporting and 18%/24% rates. How CGT works on holiday homes and investment property.
→CGT on Inherited Property
Probate value as your base cost, allowable deductions and worked example of CGT on an inherited property sale.
→CGT on Buy-to-Let
Capital gains tax when selling a buy-to-let property - allowable costs, 2026/27 rates and a worked example.
→Capital Gains Tax Losses
How capital losses reduce taxable gains, when losses carry forward and how they interact with the annual exempt amount.
→CGT Reporting Deadlines
The 60-day rule for residential property and Self Assessment deadlines for other gains - what you must report and when.
→CGT for Basic-Rate Taxpayers
How CGT is calculated when your income stays within the basic-rate band and why large gains can still hit 24%.
→CGT on a Business Sale
Business Asset Disposal Relief at 18% for qualifying business sales - who qualifies and how it reduces your CGT bill.
→CGT for Higher-Rate Taxpayers
When your income exceeds £50,270 all your taxable gains are charged at 24% - how that works and what reduces the bill.
→CGT for Higher-Rate Taxpayers - Full Guide
How income interacts with CGT, worked example at £60k income, partial-rate scenarios and planning options.
→CGT on Gifts
Giving an asset can trigger CGT at market value - gifts to children, spouses, charities and when Hold-Over Relief applies.
→CGT Records
What records to keep for HMRC, how long to keep them and what happens if records are lost or incomplete.
→How to Calculate Capital Gains Tax
Step-by-step: gross gain, losses, AEA, income band split and 18%/24% rates - with full worked examples.
→CGT Rates 2026/27 - Full Guide
18%/24% main rates on most assets since October 2024. What changed, BADR at 18% from April 2026, the AEA and worked rate examples.
→CGT Allowance 2026/27 - £3,000 AEA
The annual exempt amount is £3,000. How it has been cut, the use-it-or-lose-it rule and how to make the most of it.
→CGT on Property UK 2026/27
18%/24% on second homes and buy-to-let since April 2024. Allowable costs, 60-day rule and planning strategies.
→CGT on Shares UK 2026/27
18%/24% on shares outside ISAs. Section 104 pooling, the 30-day rule and bed-and-ISA strategy explained.
→The CGT 30-Day Rule
The bed-and-breakfast rule: how it works, why it matters for loss crystallisation and the ISA exception.
→BADR - 18% CGT Rate on Business Sales
Business Asset Disposal Relief at 18% on up to £1m lifetime, falling to £500,000 for sales from 6 April 2027 (Budget 2026). Qualifying conditions, worked example and risks.
→CGT in Scotland 2026/27
CGT rates are the same in Scotland, but the lower Scottish income tax threshold affects which CGT band applies.
CGT calculators
Free tools to estimate capital gains tax on different asset types for 2026/27.
UK Capital Gains Tax Calculator
Estimate CGT on any disposal - shares, property, crypto or other assets. Enter proceeds, cost, losses and income.
→Property CGT Calculator
Estimate capital gains tax on a second home, buy-to-let or inherited property using 2026/27 rates.
→Shares CGT Calculator
Calculate CGT on shares, funds and other investment assets held outside an ISA or pension for 2026/27.
→Crypto CGT Calculator
Estimate capital gains tax on cryptocurrency disposals for 2026/27, including pooling basics.
→CGT Allowance Calculator
Calculate how much of your £3,000 annual exempt amount remains after your gains for 2026/27.
→Capital Gains Tax Property Calculator
Dedicated CGT calculator for UK property sales. Enter purchase price, improvements, sale price and income for a full estimate.
Capital gains tax - common questions
What is the CGT annual exempt amount for 2026/27?
What are the CGT rates for 2026/27?
How does my income affect my CGT rate?
Can I use capital losses to reduce my CGT bill?
Does the calculator handle my main home?
Are crypto disposals subject to CGT?
When do I need to report a property gain?
Independent and free to use, not part of HMRC. Reviewed by the UKCapitalGainsTaxCalculator team. Read our methodology, editorial standards and sources.
How we calculate CGT
We calculate the gross gain (sale proceeds minus purchase cost and allowable costs), deduct capital losses and the £3,000 annual exempt amount, then split the taxable gain across the 18% and 24% CGT bands. Your taxable income before the gain determines how much basic-rate band (£37,700) remains.
This calculator does not handle private residence relief, lettings relief, Business Asset Disposal Relief, non-UK residents, trusts, or complex share matching. It is a simplified estimate for standard individual disposals.
Reviewed by the UKCapitalGainsTaxCalculator team.
Every figure is checked against current HMRC and GOV.UK guidance and reviewed for the 2026/27 tax year. We explain how the tax works in plain English with worked examples, not just numbers. Editorial standards · Sources · About us