2026/27 tax year · your own figures · PDF + spreadsheet
Check your Capital Gains Tax before you report it
Your full computation, a personalised review of the costs, losses and reliefs people miss, your deadline and how to report, worked out from your own figures. Before you pay HMRC, check every cost, loss and relief is in your figures.
- Full computation, 18% / 24%
- Up to 8 quick checks
- Your deadline date
- Costs tracker spreadsheet
£4.99 one-off · instant download · no account · fill in your figures ↓
Not useful? Full refund via our contact form.
Checked against official sources (GOV.UK and HMRC) on 15 October 2026. General information, not tax advice.
Fill in or check your figures
Everything is optional except what you sold it for. We store these numbers (no name, email or address) only to produce your report after payment.
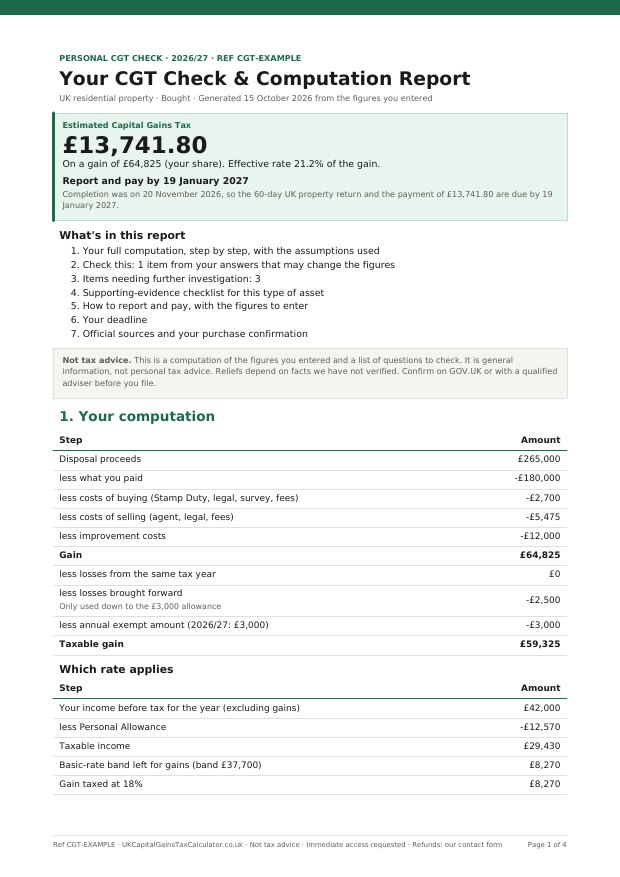
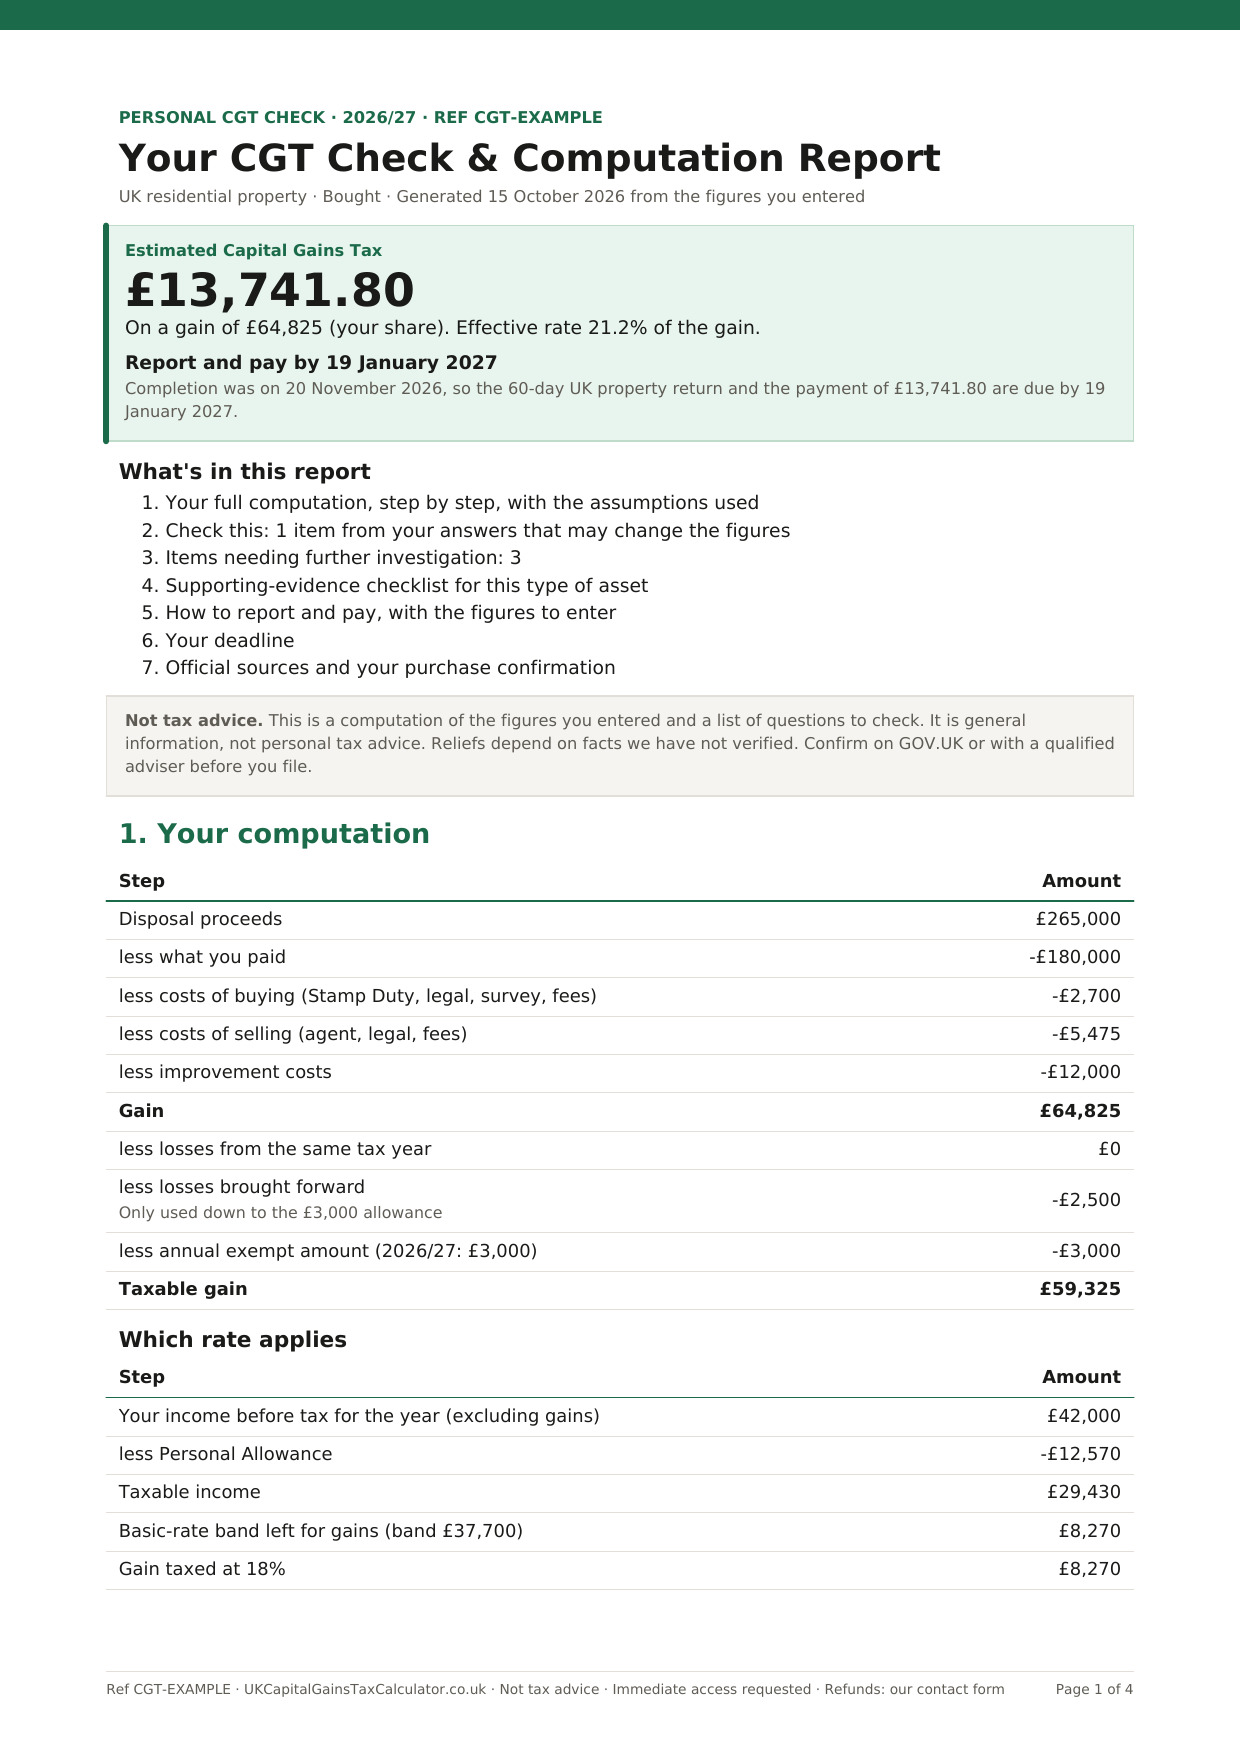
A buy-to-let sale, worked through
Bought in 2015 for £180,000 (£2,700 of buying costs), a £12,000 kitchen and bathroom, sold for £265,000 (£5,475 of selling costs) completing on 20 November 2026. Salary £42,000, £2,500 of losses brought forward, married.
| Disposal proceeds | £265,000 |
| less what was paid and allowable costs | -£200,175 |
| Gain | £64,825 |
| less losses brought forward | -£2,500 |
| less annual exempt amount | -£3,000 |
| Taxable gain | £59,325 |
| £8,270 at 18% (basic-rate band left) | £1,488.60 |
| £51,055 at 24% | £12,253.20 |
| Capital Gains Tax | £13,741.80 |
| Report and pay by 19 January 2027 | |
Every figure above is produced by the same code that writes your report.
How the report differs from our guides
| This report (£4.99) | Survival Pack (£4.99) | Tax Pack Library (£9.99) | |
|---|---|---|---|
| What it is | A computation and review of your sale | A general 20-page guide to the CGT rules | All 7 of our tax guides, including the Survival Pack |
| Uses your figures | Yes: your gain, your tax, your deadline date | No: worked examples and blank worksheets | No |
| Spots possible omissions | Yes: what each missing cost, loss or relief would change, in pounds | Explains the reliefs in general | Explains the reliefs in general |
| Best for | Checking before you report and pay | Understanding the rules first | People with several tax questions |
Read about the Survival Pack or the Tax Pack Library.
Frequently asked questions
What do I get?
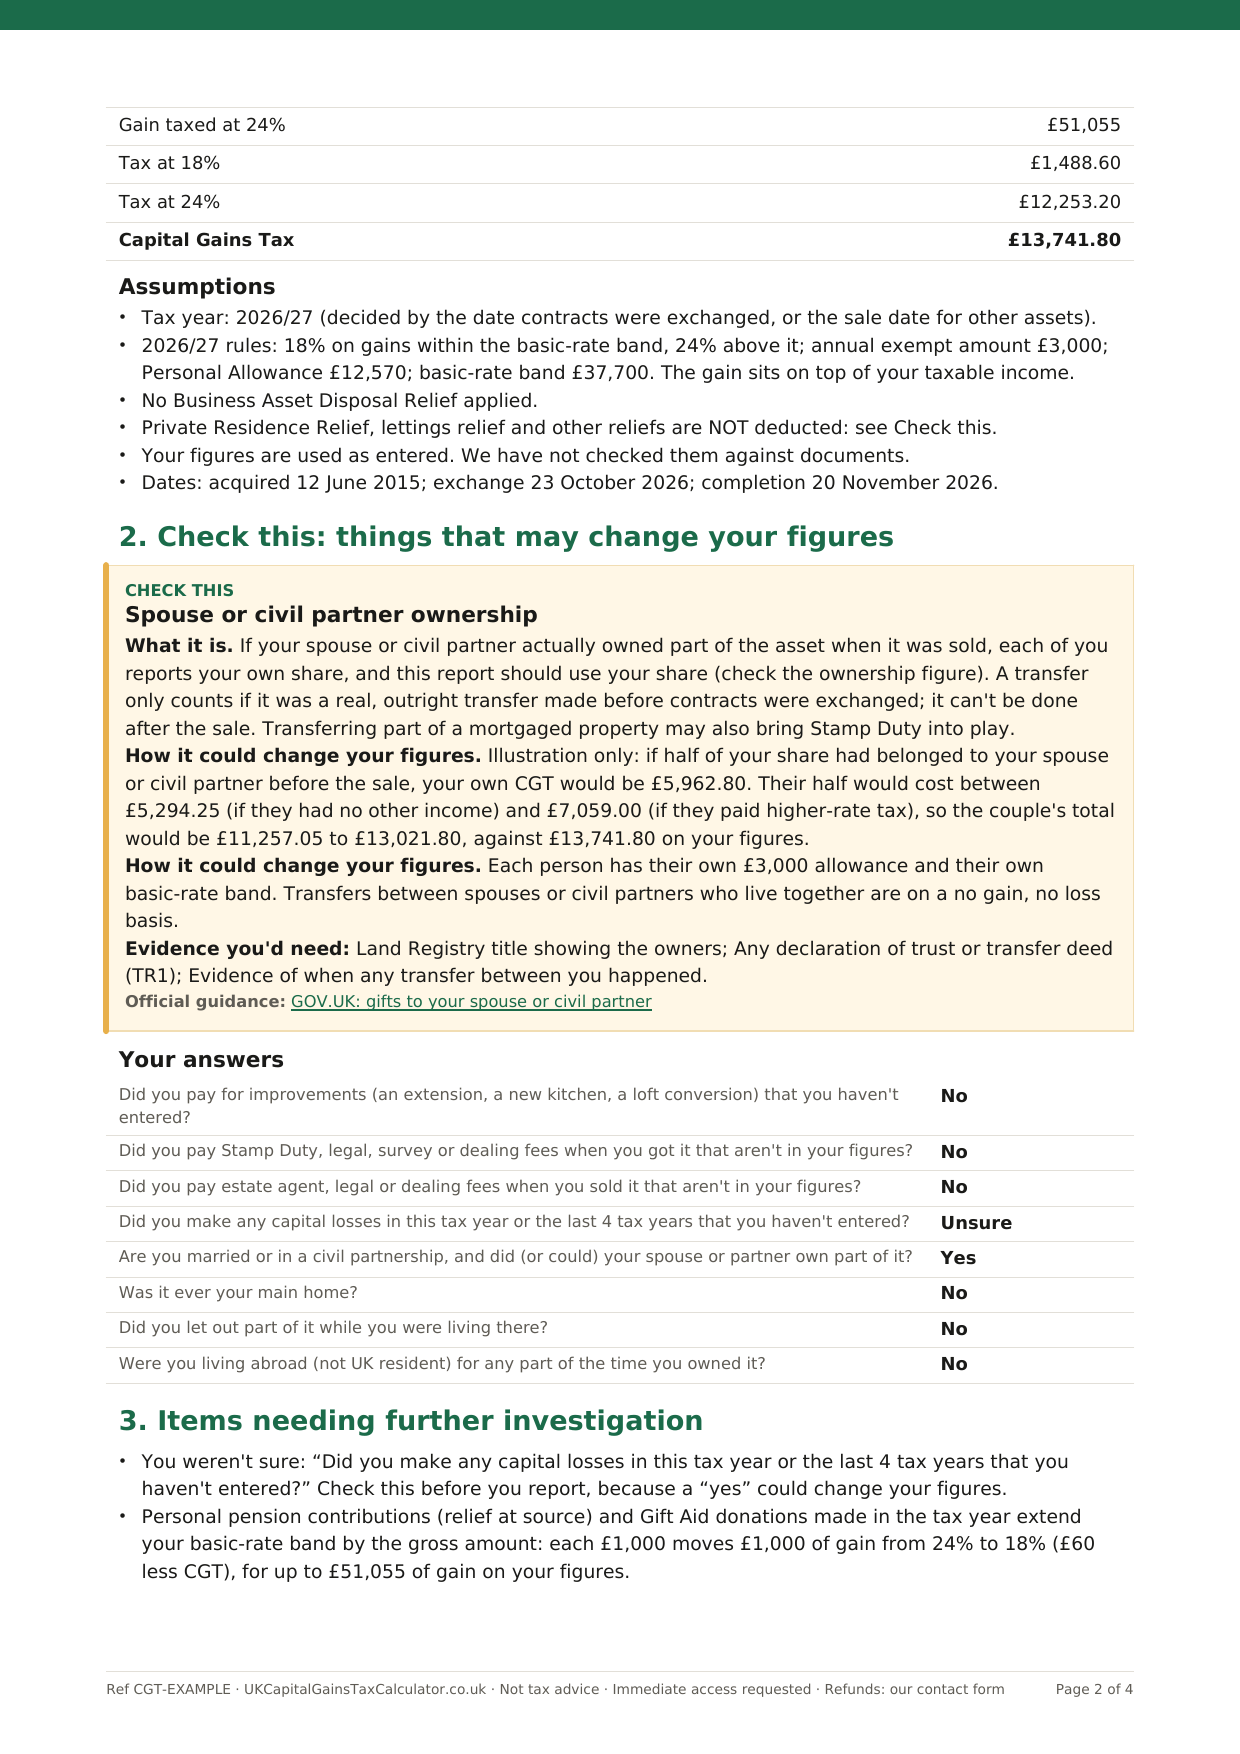
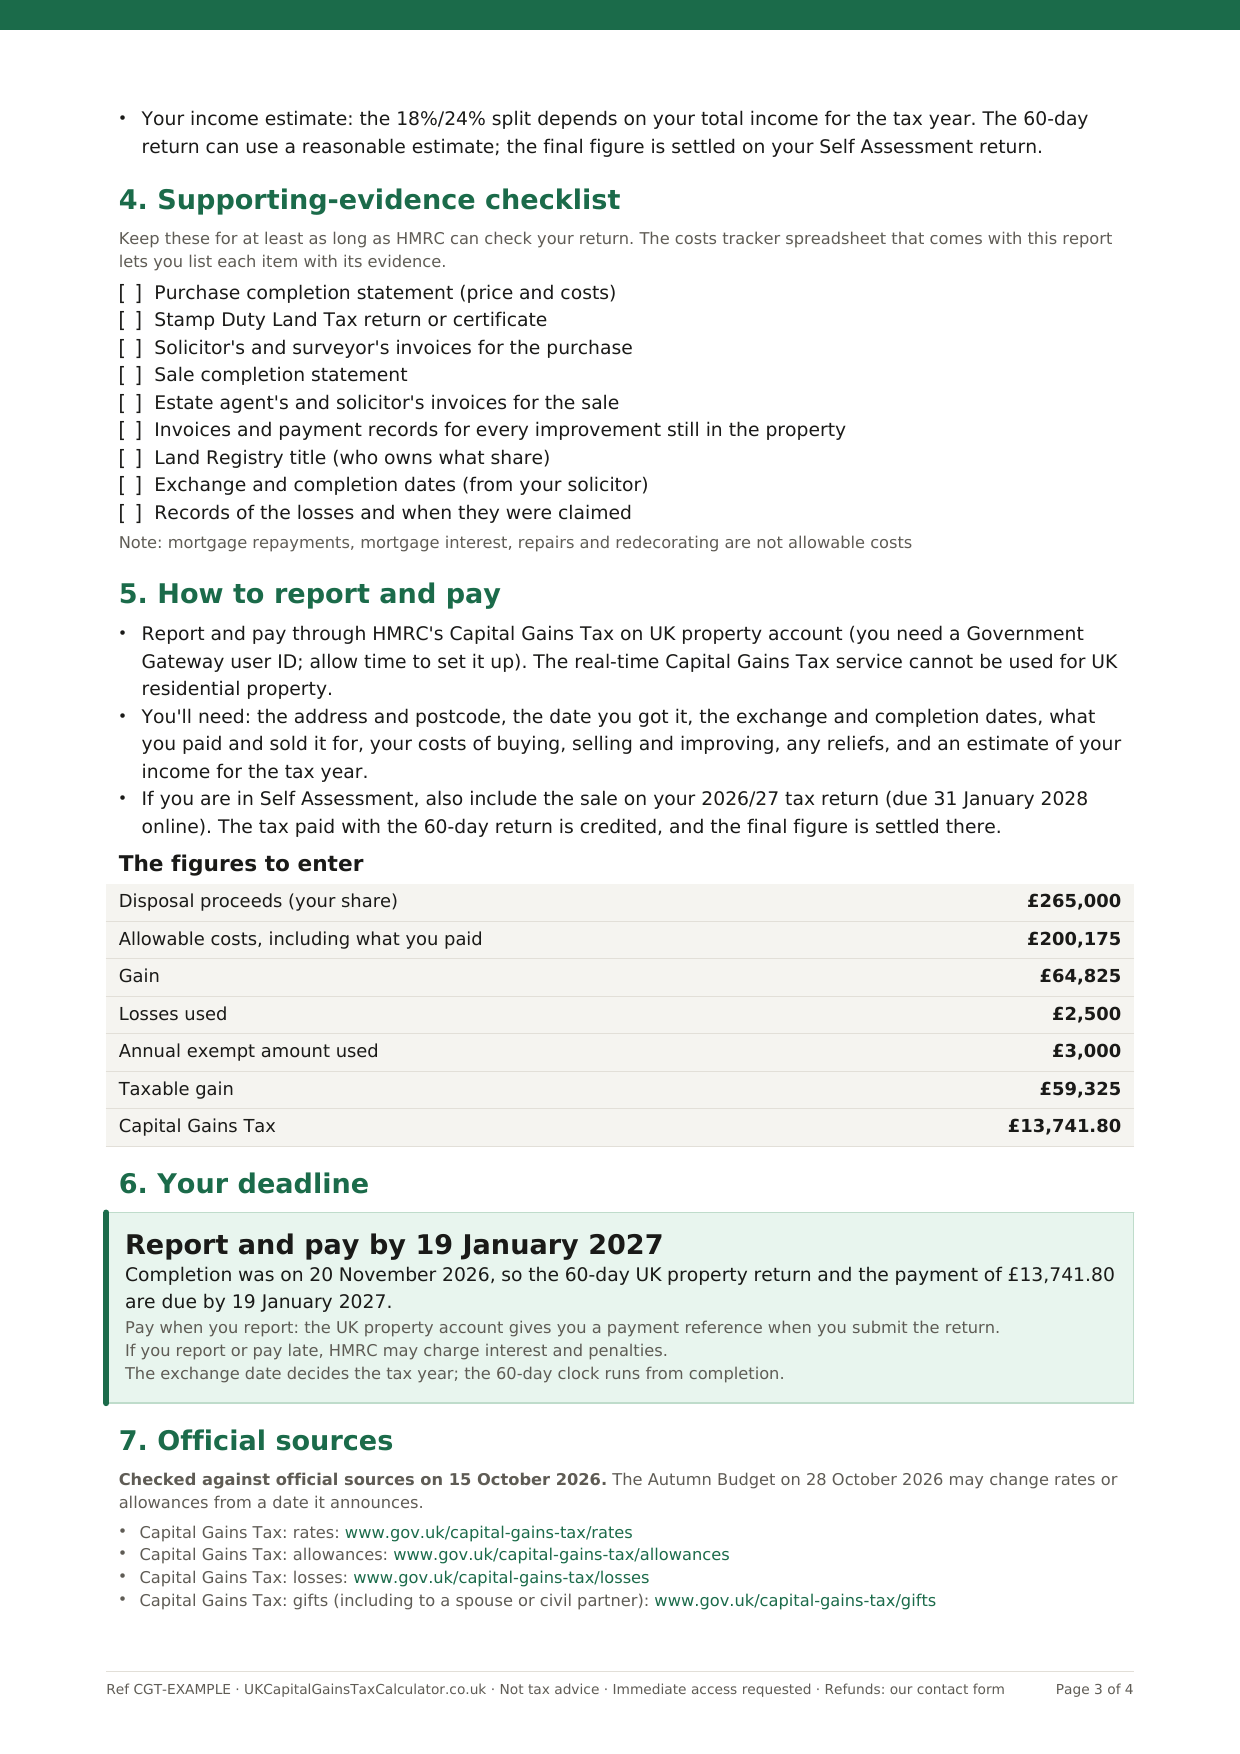
A PDF report of your own figures for 2026/27: the full computation, the 18%/24% split using your income, a Check this section for every answer that may change the figures, items to investigate, an evidence checklist for your type of asset, how to report and pay, your deadline and the official sources. You also get a spreadsheet to track each allowable cost and its evidence. Both download straight after payment; the links work for 30 days.
How is it different from the Survival Pack?
The Survival Pack is a general 20-page guide to the rules, the same for everyone. The report is about your sale: it works through your numbers, shows what each possible omission would change in pounds, and gives your deadline date. Many people use both.
Do I have to type my figures again?
No. If you have used one of the calculators on this site, the form is filled in from it. Check the figures, answer up to eight optional yes/no questions, and pay.
Will it tell me which reliefs I can claim?
No. It shows what each relief or missing cost would change if it applies, and what you would need to check and keep as evidence. Whether a relief applies depends on facts we have not verified.
Can I use it to report to HMRC?
It gives you the figures HMRC asks for and explains which service to use. The real-time Capital Gains Tax service asks you to attach your own calculation; the computation in the report can be that. You still report and pay yourself.
Is it personal tax advice?
No. It is a computation of the figures you enter and a list of questions to check. For complex disposals, business sales or anything high value, speak to a qualified tax adviser.
What if it isn't useful?
Use our contact page and we'll refund you in full.
Not tax advice: the report is a computation of the figures you enter and a list of questions to check. It is general information, not personal tax advice, and it never says you are entitled to a relief. Rules checked against GOV.UK and HMRC on 15 October 2026; the Autumn Budget on 28 October 2026 may change them.